Container as a Service Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Container as a Service Market Summary
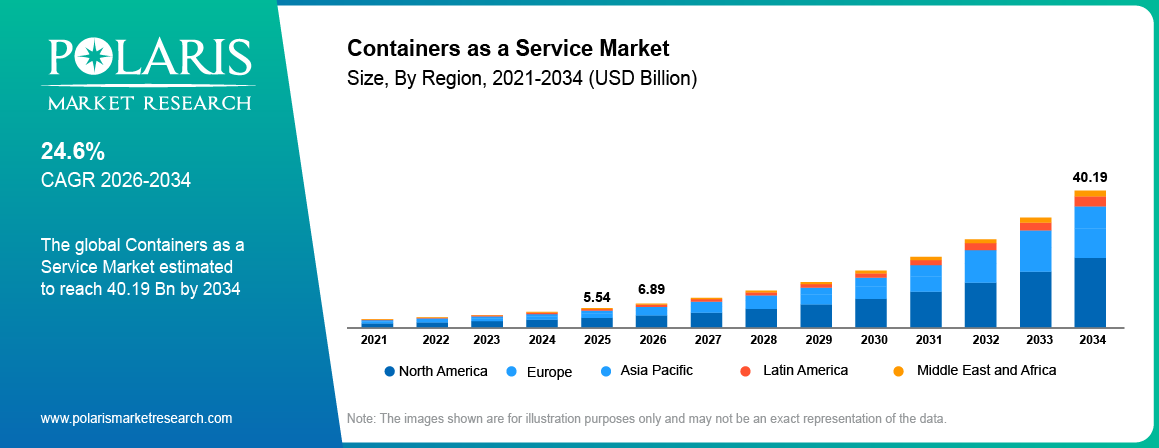
The global container as a service market size was valued at USD 5.54 billion in 2025, growing at a CAGR of 24.6% from 2026 to 2034. Growing demand for scalable, agile application deployment is driving enterprises to adopt container-based cloud services for faster development cycles. Rising adoption of microservices and DevOps practices increases reliance on containers, boosting demand for managed container services.
Market Statistics
Container as a Service Market Key Takeaways
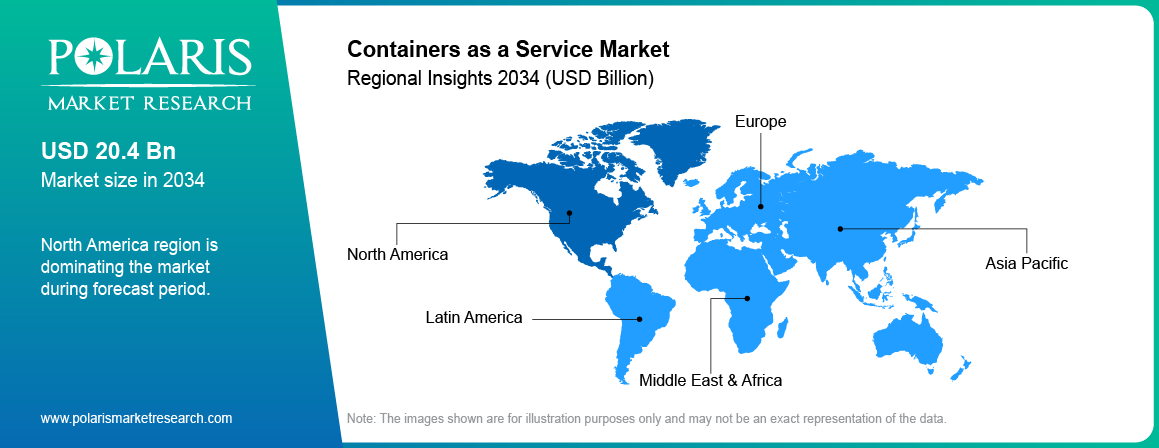
- The North America containers as a service market held 35.10% of the revenue share in 2025. The early adoption of cloud-native technologies across the region and increasing investments in enterprise digital infrastructure drive the regional market growth.
- The market in Asia Pacific is expected to register the highest CAGR of 26.7% from 2026 to 2034, driven by rapid digital transformation and cloud adoption among emerging economies.
- The management & orchestration segment led the market with 30.21% of the revenue share in 2025. The rise of complex, containerized environments across enterprises propels the demand for robust orchestration platforms.
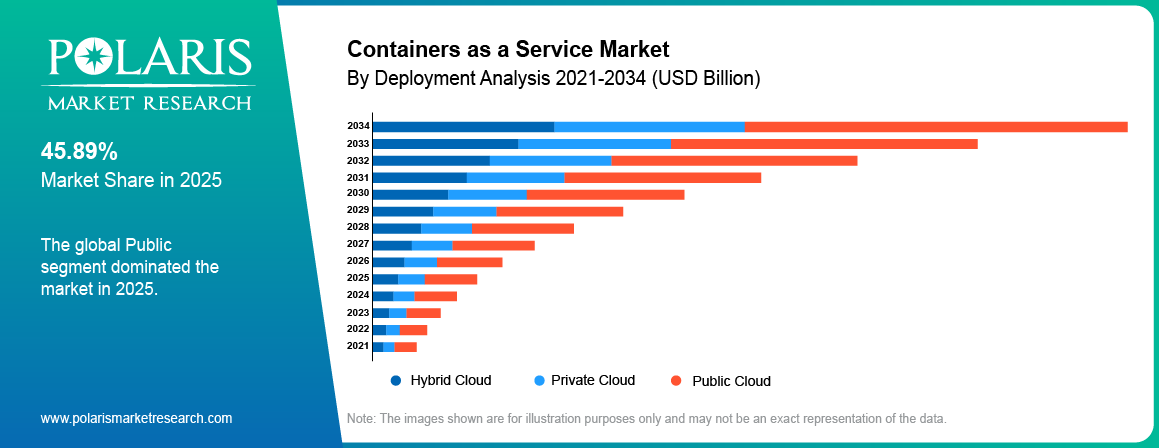
- The public cloud segment held 45.89% of the revenue share in 2025. Enterprises increasingly preferred public cloud providers for their container workloads due to the scalability, lower upfront investments, and broad service ecosystem.
- The small & medium enterprises (SMEs) segment is expected to record a significant CAGR of 26.3% during 2026–2034. It is supported by rising interest in agile development and digital transformation.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Is Containers as a Service?
The containers as a service market refers to a cloud-based service model that enables users to manage and deploy containerized applications using orchestration tools. It streamlines container lifecycle management, offering scalability, portability, automation, and reduced infrastructure complexity. The rising adoption of microservices architecture is allowing organizations to build scalable, decoupled applications effectively. Containers play a pivotal role in this paradigm by encapsulating services, which facilitates independent development, testing, and deployment processes. This trend is significantly boosting the demand for Container as a Service (CaaS) platform, which enhance application lifecycle management by providing streamlined orchestration and management solutions for containerized applications.
Containers offer unmatched application portability across cloud, on-premises, and hybrid environments. CaaS enhances this flexibility by managing scaling and deployment seamlessly, appealing to enterprises seeking agility and consistent performance across dynamic IT environments.
How Does Containers as a Service Work?
Container as a service allows businesses to run and manage applications inside containers through a cloud platform. Developers package an application and its required files into a container. The CaaS provider then deploys, manages, and scales these containers. Users can add or remove computing resources based on demand. This reduces the need to manage physical servers. CaaS also supports faster application development, easier deployment, and better resource use across cloud environments.
CaaS vs PaaS vs IaaS
| Feature | IaaS (e.g., AWS EC2) | PaaS (e.g., AWS Elastic Beanstalk) | CaaS (e.g., AWS EKS, Azure AKS) |
| Infrastructure Managed By | User manages OS, runtime, middleware | Provider manages OS, runtime; user manages code | Provider manages cluster; user manages containers & workloads |
| Abstraction Level | Low (raw compute/storage) | High (application-centric) | Medium (container-centric, granular control) |
| Container Support | Manual setup required | Limited, app-level abstraction | Native; Kubernetes-based orchestration |
| Portability | Low (VM-tied) | Medium (platform-dependent) | High (run anywhere with container runtime) |
| Scalability | Manual or auto-scale (coarser) | Auto-scale (app-level) | Auto-scale at container and cluster level |
| Developer Control | Full control, high complexity | Low control; fast deployment | High control with reduced infrastructure burden |
| Best For | Custom OS, legacy workloads, VMs | Rapid app deployment, low DevOps overhead | Microservices, CI/CD, cloud-native, hybrid workloads |
| Pricing Model | Per VM/resource hour | Per app instance / compute unit | Per node, pod, or request (serverless CaaS) |
Source: Polaris Market Research Analysis
Market Dynamics
Driver: Rising Adoption of DevOps Practices
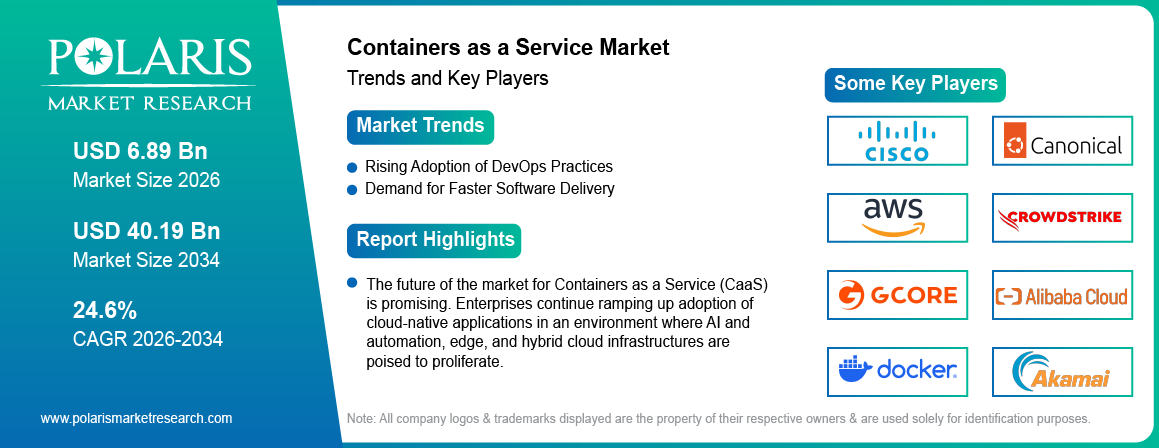
Increasing adoption of DevOps practices drives the container as a service market growth. DevOps has become a core part of modern software development. It promotes collaboration between development and operations teams to improve the speed and quality of software delivery. DevOps encourages continuous integration and continuous delivery (CI/CD). They require consistent and scalable environments for building, testing, and deploying applications. CaaS provides automation, real-time monitoring, orchestration, and container lifecycle management that align perfectly with DevOps workflows. These capabilities enable teams to maintain efficiency and reliability throughout the development pipeline. CaaS fits naturally into DevOps ecosystems, helping organizations deliver better software faster while minimizing operational burdens. This makes CaaS integral to modern software development pipelines.
Driver: Demand for Faster Software Delivery
Rising demand for faster delivery of software among enterprises fuels the CaaS market growth. Enterprises are under pressure to release software updates quickly to stay competitive and meet user expectations. Rapid innovation, evolving customer needs, and shorter product lifecycles require fast, frequent deployment cycles. Containers as a Service enables this by streamlining the deployment and management of containerized applications. It automates key processes such as provisioning, scaling, and monitoring, allowing developers to focus on writing code rather than managing infrastructure. Teams build, test, and release applications faster and more reliably, reducing the time-to-market for new features. This speed and agility make CaaS a valuable asset for organizations embracing agile methodologies.
Driver: AI-Powered Container Orchestration & Automation
AI is making container management easier and more automated. AI-driven tools can manage container performance, predict resource requirements, and detect potential failures. They also automate the deployment and scaling of containers. Tools such as Kubernetes, Google Kubernetes Engine, and Amazon EKS offer automated container management. The tools are used in applications such as autoscaling during heavy traffic and optimizing workloads. They also help in detecting failures and self-healing applications. These features reduce the human intervention, thereby driving the growth.
Driver: Microservices Architecture & Cloud-Native Development
Microservices architecture deployment is driving the Container as a Service (CaaS) market growth. This approach recommends dividing an application into several independent services that are easier to build and maintain. These services enable faster feature delivery and shorter development cycles. Using microservices makes it possible to deploy applications in containers. This ensures better isolation of components and more consistent operation. Designing cloud-native applications supports a more agile approach to software development. Technologies such as Docker container services and Kubernetes are used to simplify and automate the management of containers. Companies are now focusing on modernizing legacy applications and developing new cloud-native ones, thereby increasing the demand for CaaS platforms.
Driver: Security and Data Protection Requirements
The growing importance of data security and protection driving the CaaS industry growth. Organizations need to safeguard their applications and data from an increasing number of cyber-attacks. The CaaS platforms offer features such as access control, container scanning, encryption, and threat detection. These tools enable businesses to detect and mitigate potential attacks in operations. Many firms are willing to invest in products and technologies that improve data security with the rising complexity and frequency of cyber-attacks.
Driver: Regulatory Compliance and Data Governance
The need to comply with regulatory standards is fueling the growth of the CaaS market. Many industries are subjected to stringent rules regarding data governance, especially the financial and healthcare services and government sectors. The container as a service platform enables enterprises to manage access control and security features while meeting compliance and governance standards. They further provide a consistent set of rules for deploying and operating in different environments, including hybrid and multi-clouds. This feature allows businesses to remain compliant with industry-specific regulations.
Restraint: Complexity and High Cost of Container Management
Container management can be complicated to handle, particularly for organizations with less skilled workers. Enterprises require adequate control of all network connections and the right allocation of resources. Implementation of effective security measures is also needed. Additionally, companies face higher costs to maintain competence in the field, particularly for Kubernetes container management. For small and medium-sized organizations, adopting such technologies and processes is expensive. These factors restrain the container as a service industry growth.
Restraint: Rising Security Concerns
Containers can create security concerns if they are not properly configured and monitored. A security issue in one container image may affect multiple applications. Organizations need to ensure regular scans, checks, access controls, and data protection mechanisms to get reliable results. At the same time, security concerns are rising with the rising incidents of data breaches and cyberattacks. Due to rising concerns on data security, organizations are becoming reluctant to adopt the CaaS model. The sensitivity of the information and the threat of cloud computing failures are especially worrying for organizations in regulated/compliance-heavy industries.
Opportunity: Rising Demand for Edge Compute and Hybrid Cloud
The rising demand for edge compute and hybrid cloud represents a major opportunity for the CaaS market. Edge computing enables organizations to place their applications wherever they need to be to ensure optimal performance. Moreover, such solutions are typically light. Thus, they can run reliably on a variety of hardware and software. Companies are expected to turn to CaaS with the growing need for flexible hosting and application management solutions. Additionally, the increasing reliance on IoT devices and the rise of 5G is expected to fuel the demand for cloud-based solutions.
Segmental Insights
| Dimension | Segment | 2025 Revenue Share and CAGR (2026-2034) | Fastest-Growing Sub-Segment |
| Service Type | Management & Orchestration | 30.21% | Monitoring & Analytics (highest CAGR 2025–2034) |
| Deployment | Public Cloud | 45.89% | Hybrid Cloud (fastest CAGR; data sovereignty, edge use cases) |
| Enterprise Size | Large Enterprises | 61.8% | Small & Medium Enterprises (pay-as-you-go adoption accelerating) |
| End Use | IT & Telecommunication | 29.6% | Retail (e-commerce, seasonal scaling, personalization) |
| Region | North America | 35.10% | Asia Pacific (digital transformation, 5G rollout) |
Source: Polaris Market Research Analysis
Service Type Analysis
Based on service type, the segmentation includes management & orchestration, security, monitoring and analytics, storage and networking, and others. The management & orchestration segment dominated the market with 30.21% of the revenue share in 2025. Complex, containerized environments across enterprises created the need for robust orchestration platforms. These platforms help handle deployment, scaling, and operational management. Tools such as Kubernetes have become essential for managing containers at scale. They ensure seamless application delivery and performance. Many organizations prioritized investments in orchestration to gain better control over containerized workloads. It also helps reduce downtime and improve resource utilization. These benefits propel the container orchestration platform market growth.
The monitoring and analytics segment is expected to register the fastest CAGR of 27.8% from 2026 to 2034. The growth is driven by the increasing demand for real-time visibility into containerized applications. Organizations are relying on data-driven insights to detect performance issues, ensure compliance, and enhance application reliability. Advanced analytics tools integrated into CaaS platforms help detect anomalies, predict system failures, and optimize container performance. The need to maintain service-level agreements (SLAs) and improve incident response times has pushed enterprises to adopt intelligent monitoring systems. Growth in distributed, cloud-native infrastructure applications further adds complexity. Therefore, advanced observability tools are becoming a key priority for future-ready infrastructure.
Container as a Service Market: By Service Type
| Service Type | Core Functions | Typical Offerings / Examples | Primary Value |
| Management & Orchestration | Container deployment, scheduling, scaling, load balancing, and lifecycle management. | Managed Kubernetes, Docker management, Amazon ECS, Azure Kubernetes Service, Google Kubernetes Engine. | Simplifies large-scale container operations and improves resource utilization. |
| Security | Vulnerability scanning, identity and access management, image security, runtime protection, and compliance monitoring. | Container image scanning, secrets management, admission control, zero-trust security, policy enforcement. | Protects container workloads and supports regulatory compliance. |
| Monitoring & Analytics | Performance monitoring, log management, observability, resource tracking, and usage analytics. | Application performance monitoring, centralized logging, metrics dashboards, distributed tracing, anomaly detection. | Improves visibility, availability, and troubleshooting across dynamic environments. |
| Storage & Networking | Persistent storage, container networking, service discovery, backup, and data recovery. | Container-attached storage, software-defined networking, virtual networks, storage orchestration, backup services. | Enables reliable data access and communication between containers. |
| Others | CI/CD, consulting, training, technical support, maintenance, and migration services. | DevOps automation, container modernization, managed support, cloud migration, professional services. | Accelerates adoption and reduces operational complexity. |
Source: Polaris Market Research Analysis
Deployment Analysis
In terms of deployment, the segmentation includes public cloud, private cloud, and hybrid cloud. The public cloud segment held 45.89% of the revenue share in 2025. Enterprises increasingly preferred public cloud providers for their container workloads. This was due to scalability, lower upfront investment, and a broad ecosystem of services. Major players provided robust CaaS solutions with built-in orchestration, monitoring, and security features, enabling rapid deployment and minimal infrastructure management. The flexibility to manage fluctuating workloads without hardware constraints attracted both large organizations and startups. The trend toward cloud-first strategies and rapid digital transformation across industries further strengthened the dominance of public cloud-based container deployments.
The hybrid cloud segment is expected to register the highest CAGR of 26.9% from 2026 to 2034. The growth is supported by enterprises seeking greater flexibility, control, and data governance. Many organizations are integrating on-premise infrastructure with public cloud platforms to manage sensitive workloads while leveraging the cloud for scalability. CaaS plays a vital role in enabling seamless container orchestration across hybrid environments. The ability to deploy, monitor, and scale applications across multiple clouds and on-premise systems appeals to industries with regulatory concerns and data sovereignty requirements. Increased focus on workload portability, disaster recovery, and operational resilience fuels the hybrid cloud deployment market expansion.
The private cloud segment recorded substantial share of 22.15% in 2025 due to growing concerns about data security, regulatory compliance, and control of the container workload. Financial institutions, healthcare organizations, government agencies, and other enterprises with critical data and applications are increasingly adopting private cloud over public cloud or hybrid solutions. The growing need for hybrid IT, the rise in demand for customized infrastructure, and the requirement for reliable performance are driving the demand for private cloud CaaS. The need for automation and orchestration of containers and orchestration tools is further prompting many enterprises to transform their legacy systems into a more agile environment that runs on private cloud infrastructure, thereby driving the segment.
Enterprise Size Analysis
In terms of enterprise size, the segmentation includes small & medium enterprises, and large enterprises. The large enterprises segment held the largest revenue share of 61.8% in 2025. The leading position is attributed to their high-volume container deployments and complex application environments. These organizations often operate across multiple geographies and require advanced orchestration and monitoring capabilities to ensure uptime and performance. The need for strong governance, security frameworks, and centralized management pushed large-scale businesses to adopt sophisticated CaaS platforms. Budget flexibility and existing investments in DevOps pipelines also contributed to wider adoption. Moreover, these enterprises are continuously optimizing infrastructure to improve operational efficiency, which has made them key adopters of automated container management tools.
The small & medium enterprises segment is expected to register a significant CAGR of 26.3% from 2026 to 2034. The growth is supported by growing interest in agile development and digital transformation. Many SMEs are adopting CaaS to simplify application deployment without investing heavily in infrastructure or personnel. Cloud-native development is becoming more accessible, enabling faster time-to-market and improved scalability for smaller firms. The flexibility of pay-as-you-go models, along with the availability of managed container services, allows SMEs to focus on product innovation rather than backend operations.
End Use Analysis
In terms of end use, the segmentation includes IT & telecommunication, BFSI, healthcare, retail, manufacturing, government, transportation & logistics, and others. The IT & telecommunication segment held the largest revenue share of 29.6% in 2025 due to its high demand for scalable, high-performance application infrastructure. Telecom providers and tech companies rely on containerized microservices to support dynamic services such as 5G, edge computing, and cloud platforms. These workloads require seamless orchestration and rapid deployment, which are well-supported by CaaS solutions. The sector also benefits from a mature DevOps culture and strong automation investments. High service-delivery expectations and the growing need for efficient resource management are boosting CaaS adoption in this segment.
The retail segment is expected to register a significant CAGR of 27.2% from 2026 to 2034. Increasing need for digital agility, personalized customer experiences, and real-time analytics propel the segment growth. Retailers are leveraging CaaS to support eCommerce platforms, recommendation engines, and inventory systems that require continuous updates and fast scalability. Containerized applications help streamline omnichannel operations and improve backend integration across stores, warehouses, and digital touchpoints. Seasonal traffic spikes and changing consumer behavior demand a flexible infrastructure that CaaS can deliver. The ability to reduce deployment time and experiment with new services quickly makes container platforms particularly attractive for retail businesses.
| End User | Key CaaS Applications | Primary Adoption Drivers |
| IT & Telecommunication | Cloud-native application development, microservices, 5G network functions, and DevOps automation. | High workload volumes, hybrid-cloud adoption, and need for rapid software deployment. |
| BFSI | Digital banking, mobile payments, fraud detection, trading platforms, and customer applications. | Data security, regulatory compliance, scalability, and continuous application availability. |
| Healthcare | Telemedicine, electronic health records, medical analytics, and connected healthcare applications. | Demand for secure data management, interoperability, and scalable digital healthcare services. |
| Retail | E-commerce platforms, recommendation engines, inventory management, and omnichannel applications. | Seasonal scalability, real-time customer engagement, and faster application releases. |
| Manufacturing | Industrial IoT, smart factories, robotics, production monitoring, and predictive maintenance. | Edge computing, automation, real-time analytics, and operational efficiency. |
| Government | Citizen-service portals, digital identity, public databases, and e-government applications. | Infrastructure modernization, data sovereignty, cybersecurity, and service availability. |
| Transportation & Logistics | Fleet management, route optimization, warehouse automation, and shipment tracking. | Real-time data processing, supply-chain visibility, and connected infrastructure. |
| Others | Media streaming, education platforms, energy systems, travel applications, and professional services. | Application modernization, flexible infrastructure, and multi-cloud deployment. |
Source: Polaris Market Research Analysis
Regional Analysis
| Region | Market Position / Growth | Key Growth Drivers | Market Characteristics |
| North America | Held 35.10% market share in 2025. | Early adoption of cloud-native technologies, strong enterprise cloud spending, and advanced digital infrastructure. | Largest and most mature CaaS market; high adoption among large enterprises and technology companies. |
| Asia Pacific | Expected to register the highest CAGR of 26.7% during 2026–2034. | Rapid digital transformation, expanding cloud adoption, and increasing technology investment in emerging economies. | Fastest-growing market, supported by startups, telecom companies, e-commerce, and digital services. |
| Europe | Expected to grow at a 22.9% CAGR during the forecast period. | Rising demand for compliance-driven cloud-native applications, particularly in BFSI and healthcare. | Strong focus on data sovereignty, cybersecurity, regulatory compliance, and hybrid cloud deployments. |
| Latin America | Expected to grow at a 23.4% CAGR during 2026–2034. | Increasing cloud adoption, modernization of IT infrastructure, and expansion of digital businesses. | Emerging market with growing demand from financial services, retail, telecommunications, and public-sector organizations. |
| Middle East & Africa | Expected to grow at a 22.6% CAGR during the forecast period. | IT infrastructure transformation and rising demand for digitized services and applications. | Adoption concentrated in telecommunications, government, banking, energy, and large enterprises. |
Source: Polaris Market Research Analysis
The North America held 35.10% of the CaaS market share 2025 due to early adoption of cloud-native technologies and strong investments in enterprise digital infrastructure. Organizations across industries have integrated CaaS platforms into their DevOps workflows to enhance application scalability, performance, and speed of delivery. Leading cloud providers and tech giants in the region have driven market maturity through innovation in orchestration and container lifecycle tools. High cloud penetration, widespread use of Kubernetes, and demand for CI/CD pipeline automation further strengthened North America's leadership in the CaaS market throughout the year.
U.S. Containers as a Service Market Insights
The U.S. CaaS market is projected to grow rapidly with a CAGR of 23.8% from 2026 to 2034. Rising demand for containerized solutions in banking, telecom, and healthcare sectors drives the market growth. These industries are shifting toward microservices-based architectures to improve application flexibility and service delivery. Government and defense entities are also investing in secure CaaS deployments to modernize IT systems. Expansion of hybrid cloud infrastructure and increased adoption of AI and machine learning applications further necessitate scalable, container-based environments. Strong collaboration between enterprises and CaaS platform providers is expected to continue fueling market growth across large and mid-sized businesses during the forecast period.
Asia Pacific Containers as a Service Market Outlook
The Asia Pacific market is expected to register the highest CAGR of 26.7% from 2026 to 2034. The growth is supported by rapid digital transformation and cloud adoption among emerging economies. Startups and tech-driven enterprises in the region are turning to CaaS platforms to enhance time-to-market, reduce operational costs, and scale services efficiently. Growing investments in smart city projects, 5G rollout, and eCommerce ecosystems are increasing demand for flexible, containerized infrastructure. Technology hubs across countries such as India, Singapore, and Indonesia are promoting cloud-native development environments, which further encourages the use of scalable container solutions managed through CaaS offerings.
China Containers as a Service Market Trends
The China market dominated with the largest share of 38.7% in 2025 due to its aggressive push toward enterprise IT modernization and cloud independence. Leading domestic cloud providers are investing heavily in Kubernetes-based services and container lifecycle automation. Industries such as manufacturing, finance, and logistics are adopting containerized microservices to support digital platforms and improve service agility. The rise of artificial intelligence and big data applications has created a need for flexible, modular environments, which containers support effectively. Government-led initiatives promoting digital infrastructure and local cloud ecosystems have also encouraged widespread adoption of CaaS platforms across both state-owned and private enterprises.
Europe Containers as a Service Market Analysis
The market in Europe is growing significantly with a CAGR of 22.9% during the forecast period. This is attributed to the increasing demand for compliance-driven cloud-native applications, especially in sectors such as BFSI and healthcare. Stricter data protection regulations, including GDPR and the EU Data Act, are increasing the need for secure and transparent infrastructure that supports data access, portability, and controlled data sharing. Enterprises across Germany, France, and the Nordics are deploying container solutions to enable seamless hybrid cloud environments while maintaining control over data flow. Growing reliance on automation, edge computing, and real-time analytics across industrial sectors is also creating new opportunities for container-based deployment models.
Latin America Containers as a Service Market Analysis
As per our CaaS market forecast 2034, the Latin American market is expected to witness a CAGR of 23.4% during 2026–2034. It is driven by the growing adoption of cloud technologies and increasing digitization of businesses. Enterprises are looking to migrate to modern cloud infrastructure to host their applications in order to remain competitive and cut costs. The growing need for cloud-based e-commerce, digital banking, and mobile applications is driving the demand for scalable application platforms. Additionally, there is a rising need among enterprises to adopt hybrid cloud strategies to gain greater control of their workloads, thereby driving the region growth.
Brazil Containers as a Service Market Analysis
The Brazil Container-as-a-Service market is expected to witness growth at a CAGR of 24.1%, driven by the increasing digitization of the country’s growing economy. Also, the rising adoption of cloud computing technologies by enterprises to transform digitally and gain a competitive advantage boosts the market expansion. The growing adoption of digital banking and online services has resulted in the need for scalable and reliable application platforms. Enterprises are further modernizing their IT infrastructure and accelerating cloud transformation strategies. The growing local startup ecosystem is further supporting the need for cloud-based application development platforms, thereby driving the growth.
Middle East and Africa Containers as a Service Market Analysis
The Middle East and Africa Container-as-a-Service market is expected to witness a CAGR of 22.6% during the forecast period. This growth is driven by businesses' need to transform their IT infrastructure to meet rising demand for digitized services and applications. Additionally, rising cloud computing investments by enterprises to build reliable and scalable cloud applications and services are further driving the market growth in the region. The growing need for digitized services, such as smart cities and digital government services, as well as rising fintech and telecom adoption rates, is further anticipated to support market growth.
Saudi Arabia Containers as a Service Market Analysis
The Saudi Arabia recorded a 31.5% Container-as-a-Service market share in 2025. The dominance is propelled by the increasing need for businesses to adopt cloud technologies to transform their operations and comply with the local government’s vision for the country’s growing digital economy. Enterprises are adopting cloud-based application development services to build scalable and reliable applications in support of the local government’s digital transformation initiatives and to remain competitive. The growing need for digitized applications, such as smart cities, digital government services, fintech, AI, and the modernization of legacy systems will augment the demand for cloud-based application development services in the country.
Real-World Use Cases for CaaS Platforms
| Use Case | Typical Industries/Functions | How CaaS Is Used | Business Value |
| Microservices-based application platforms | E-commerce, fintech, SaaS, media/streaming | Break monoliths into independently deployable services; each service runs in containers orchestrated by CaaS. | Faster feature releases, better fault isolation, independent scaling of high-traffic services. |
| CI/CD and DevOps automation tools | Software product companies, IT services, digital banks | Container images built in CI pipelines, tested in ephemeral environments, and deployed via CaaS with rolling/blue-green updates. | Shorter release cycles, fewer deployment errors, consistent dev/test/prod environments. |
| Hybrid and multi-cloud container deployment | BFSI, healthcare, manufacturing, public sector | Same container images run on-prem and across multiple clouds using Kubernetes-based CaaS for portability. | Reduced vendor lock-in, improved resilience, easier compliance with data-residency rules. |
| Elastic web and mobile backends | Retail, travel, gaming, media | Stateless APIs and web tiers hosted on CaaS; auto-scaling based on traffic spikes (sales, campaigns, events). | Handles bursty demand without over-provisioning; lower infra cost per transaction. |
| Manufacturing, utilities, government, traditional enterprises | Wrap legacy apps in containers, lift-and-shift to CaaS, then incrementally refactor to microservices. | Extends life of critical apps, improves utilization, simplifies patching and DR. | |
| Data pipelines and analytics workloads | Retail, logistics, telecom, ad-tech | Batch and streaming jobs (Spark, Flink, custom workers) packaged as containers and scheduled on CaaS. | Standardized runtime for data jobs, easier scaling during peak loads, better resource packing. |
| Edge computing and IoT backends | Industrial IoT, smart retail, energy, automotive | Lightweight containers deployed at edge sites (factories, stores, towers) managed centrally via CaaS. | Low-latency processing near devices, centralized governance, consistent updates across sites. |
| AI/ML model serving and MLOps | Tech platforms, BFSI, healthcare, ad-tech | Model inference services containerized and served on CaaS with autoscaling and versioned rollouts. | Rapid iteration on models, reliable high-throughput inference, easy A/B testing of algorithms. |
| Internal developer platforms (IDP) | Large enterprises across sectors | CaaS as the runtime layer for self-service app deployment, with templates, policies, and observability baked in. | Faster onboarding for dev teams, standardized security/compliance, reduced platform fragmentation. |
| Event-driven and serverless-style workloads | Media, logistics, marketplaces | Event processors, webhook handlers, and short-lived jobs run as short-lived containers on CaaS. | Pay-for-what-you-use scaling, simplified operations vs. managing VMs or bespoke clusters. |
Source: Polaris Market Research Analysis
Why Enterprises Are Investing in CaaS Platforms?
Enterprises are adopting the Container as a Service (CaaS) platform to reduce complexities associated with application programming. With container as a service, there is an acceleration of application deployment and scaling of resources according to demand. The Container as a Service cloud platform facilitates cloud-native and microservices-based applications. It enables enterprises to achieve higher-level functionality while shortening the software development life cycle. Additionally, it enables hybrid and multi-cloud operations and supports features such as orchestration, monitoring, and security to help organizations optimize operations. Enterprises, therefore, adopt this cloud service model to shift toward digital transformation efficiently while also shortening the path to market for new products and services.
Competitive Analysis
The competitive landscape of the containers as a service market is defined by intense innovation and evolving strategic priorities. Industry analysis indicates a strong focus on market expansion strategies, particularly through cloud-native service enhancements and differentiated orchestration capabilities. Key players are actively engaging in joint ventures and strategic alliances to strengthen their container ecosystems and expand their global footprint. Mergers and acquisitions continue to reshape the landscape, with post-merger integration focusing on unifying container management platforms and accelerating hybrid and multi-cloud offerings.
Technological advancements in areas such as serverless containers, edge deployment, and AI-based orchestration are further intensifying competition. Strategic partnerships are enabling vendors to integrate advanced analytics, security features, and monitoring tools into their offerings. The market is also witnessing increased vertical-specific customization, catering to industries with complex regulatory and operational needs. These collective efforts are positioning vendors to capture emerging opportunities across both established and developing digital infrastructure markets.
Key Players
- Akamai Technologies
- Alibaba Cloud
- Amazon Web Services
- Canonical Ltd.
- Cisco Systems, Inc.
- CrowdStrike
- Docker Inc.
- Gcore
- Google Cloud (GKE)
- Hewlett Packard Enterprise (HPE)
- IBM Corporation
- IT Outposts
- Microsoft Corporation
- SITA Airport IT GmbH
- Successive Technologies LLC
- Tencent Cloud
- VMware (Broadcom)
Vendor Positioning
| Vendor | Key Product / Service | Primary Strength | Target Segment |
| Amazon Web Services | Amazon EKS, ECS Managed Instances (Sep 2025) | Largest ecosystem; AI/ML integration; 100k node EKS clusters | Enterprises, startups, all verticals |
| Microsoft Azure | Azure Kubernetes Service (AKS), Draft tool (Jun 2025) | Enterprise integration; GitHub CI/CD; hybrid via Azure Arc | Enterprise; financial services; government |
| Google Cloud | Google Kubernetes Engine (GKE) | Kubernetes originator; AI/ML native; multicloud networking (Dec 2025) | Tech enterprises; AI/ML workloads |
| IBM (Red Hat OpenShift) | OpenShift, IBM Cloud Kubernetes Service | Governance; regulated industries; hybrid cloud; HashiCorp (acquired 2024) | BFSI; healthcare; telecom |
| VMware (Broadcom) | Tanzu Kubernetes Grid | VM-to-container migration; vSphere integration; on-prem CaaS | Legacy enterprise modernization |
| Alibaba Cloud | Container Compute Service — ACS (Jan 2025) | Serverless container platform; APAC market leader; no node/cluster management | APAC enterprises; China domestic market |
| Cisco Systems | Cisco Container Platform | Network-integrated CaaS; hybrid enterprise networking | Large enterprises; telecom; government |
| Hewlett Packard Enterprise | HPE Ezmeral, GreenLake | On-prem consumption pricing; VM+container unified control plane | Regulated industries; private cloud buyers |
| Docker Inc. | Docker Hub, Docker Desktop, Docker Scout | Developer tooling; container image registry; SME adoption | SMEs; developer teams; CI/CD pipelines |
| Gcore | Gcore CaaS (launched Feb 2024) | Serverless; pay-per-runtime; global PoP network | SMEs; developers; cost-sensitive buyers |
| Akamai Technologies | Managed Container Service (Feb 2025) | Edge delivery; 4,300+ PoPs; global CDN-native CaaS | Edge computing; media; CDN-adjacent workloads |
| Tencent Cloud | Tencent Kubernetes Engine (TKE) | China market; gaming; AI cloud infrastructure | China domestic enterprises; gaming; fintech |
| CrowdStrike | Falcon Container Security | Runtime container security; threat detection; compliance | Security-focused buyers; regulated industries |
Source: Polaris Market Research Analysis
Containers as a Service Industry Developments
- July 2026: Amazon Web Services introduced container attribute-based rules in AWS Network Firewall, enabling more granular network policy enforcement aligned to container-level context. (Source: aws.amazon.com)
- July 2026: Oracle Cloud Infrastructure updated its Kubernetes Engine (OKE) to support clusters of up to 20,000 worker nodes, expanding its position in large-scale enterprise CaaS deployments (Source: blogs.oracle.com)
- June 2026: VMware Cloud Foundation VKS 3.7 introduced an add-on management framework and Kubernetes 1.36 support, aligning with regulated hybrid buyers requiring controlled day-two operations. (Source: blogs.vmware.com)
- April 2026: AWS Interconnect–multicloud reached general availability with Google Cloud as an initial partner, improving cross-cloud Kubernetes workload portability without public internet paths. (Source: aws.amazon.com)
- May 2026: Kubernetes v1.36 released with PodGroup and topology-aware scheduling, reinforcing demand for managed CaaS platforms that operationalize these primitives (Source: kubernetes.io)
Future Outlook
The future of the market for Containers as a Service (CaaS) is promising. Enterprises continue ramping up adoption of cloud-native applications in an environment where AI and automation, edge, and hybrid cloud infrastructures are poised to proliferate. CaaS providers can be expected to deliver increased ease of management, better security, and more automation in the coming years. The development of 5G, the Internet of Things (IoT), and real-time applications will also unlock new growth opportunities. Enterprises are seeking to gain an advantage over their competitors by being able to deliver products to market faster, and the CaaS market is poised to meet the demand.
Research Methodology
- Market estimates are derived using a blend of primary and secondary research, validated through weighted-average and combined top-down/bottom-up modeling approaches.
- Secondary research covers vendor filings, cloud infrastructure and Kubernetes adoption data, DevOps and microservices deployment trends, industry journals, and paid third-party databases to build baseline estimates.
- Primary research includes interviews with key industry participants such as CaaS providers, cloud hyperscalers, DevOps engineers, and enterprise IT decision-makers, to validate accuracy and capture forward-looking insights.
- Base year considered is 2025, with a forecast provided through 2034; revenues are expressed in USD Billion.
- Parent market is identified as the global cloud computing and Platform-as-a-Service market; the addressable segment is narrowed using container orchestration and microservices adoption rates across enterprises.
- Bottom-up model aggregates regional CaaS demand across service type, deployment, enterprise size, and end use, validated against vendor revenue disclosures from AWS, Microsoft, Google Cloud, IBM, VMware, and others.
- Regional coverage spans North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America, further segmented by major countries.
- Projected 24.6% CAGR (2026–2034) reflects a weighted analysis of rising microservices and DevOps adoption, growing demand for scalable cloud-native application deployment, expanding hybrid and multi-cloud strategies, and increasing enterprise focus on operational agility.
- Findings are cross-validated across multiple estimation methods to ensure consistency, accuracy, and reliability of the final market sizing.
Containers as a Service Market Segmentation
By Service Type Outlook (Revenue, USD Billion, 2021–2034)
- Management & Orchestration
- Security
- Monitoring and Analytics
- Storage and Networking
- Others
By Deployment Outlook (Revenue, USD Billion, 2021–2034)
- Public Cloud
- Private Cloud
- Hybrid Cloud
By Enterprise Size Outlook (Revenue, USD Billion, 2021–2034)
- Small & Medium Enterprises
- Large Enterprises
By End Use Outlook (Revenue, USD Billion, 2021–2034)
- IT & Telecommunication
- BFSI
- Healthcare
- Retail
- Manufacturing
- Government
- Transportation & Logistics
- Others
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Containers as a Service Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 5.54 billion |
| Market Size in 2026 | USD 6.89 billion |
| Revenue Forecast by 2034 | USD 40.19 billion |
| CAGR | 24.6% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Container as a Service Market FAQ's
The global market size was valued at USD 5.54 billion in 2025 and is projected to grow to USD 40.19 billion by 2034.
The global market is projected to register a CAGR of 24.6% during the forecast period.
North America held 35.10% of the revenue share in 2025 due to early adoption of cloud-native technologies and strong investments in enterprise digital infrastructure.
A few of the key players in the market are Canonical Ltd; Cisco Systems, Inc.; CrowdStrike; Docker Inc.; Gcore; Hewlett Packard Enterprise (HPE); IBM Corporation; IT Outposts; Microsoft Corporation; SITA Airport IT GmbH; Successive Technologies LLC; Tencent Cloud; and VMware (Broadcom).
The management & orchestration segment dominated the market with 30.21% of the revenue share in 2024 as the rise of complex, containerized environments across enterprises created the need for robust orchestration platforms to handle deployment, scaling, and operational management.
The public cloud segment held 45.89% of the revenue share in 2025. Enterprises increasingly preferred public cloud providers for their container workloads due to the scalability, lower upfront investment, and broad ecosystem of services offered.
Cloud-native adoption, microservices, automation, hybrid cloud deployment, and rising demand for scalable applications are major market growth drivers.
CaaS is a cloud service that helps businesses deploy, manage, and scale containerized applications without managing complex infrastructure.
BFSI, healthcare, IT, telecommunications, retail, manufacturing, and government sectors increasingly use CaaS for flexible and scalable application deployment.
CaaS enables faster application deployment, automated scaling, easier management, and efficient development of cloud-native applications across different computing environments.
CaaS offers faster deployment, scalability, automation, better resource use, reduced infrastructure management, and flexibility across hybrid and multi-cloud environments.
The market will grow with increasing adoption of AI, automation, edge computing, cloud-native applications, and hybrid cloud infrastructure.
Download Sample Report of Container as a Service Market
Please fill out the form to request a customized copy of the research report.